Summary
Paying for assisted living without selling your house is possible through several financial strategies that allow families to preserve homeownership while managing care costs. Explore these key payment options to find what works best for your situation.
- Access home equity through a HELOC, home equity loan, or reverse mortgage (age 62+) to cover assisted living expenses without an immediate sale
- Generate ongoing income by renting your property, with property management companies available to handle tenant and maintenance responsibilities
- Investigate VA Aid and Attendance benefits if your loved one is a veteran or surviving spouse, as these can help cover long-term care costs
- Review existing long-term care insurance policies and life insurance options, including life settlements or accelerated death benefits, for potential funding sources
- Work with a financial advisor or elder law attorney to understand how different strategies affect taxes, estate plans, and long-term financial goals
For many families, paying for assisted living without selling a house is an important part of planning a move. A longtime home can hold financial value as well as decades of memories, so selling it right away may not feel like the right choice.
Fortunately, several senior living payment alternatives may help families cover expenses while retaining ownership of a home. Understanding the possibilities can make it easier to compare options and decide what fits your family’s finances and long-term plans.
Using Home Equity for Assisted Living Costs Without a Home Sale
Home equity may provide access to funds without requiring an immediate sale.
Depending on the homeowner’s financial circumstances, options may include:
- Home Equity Line of Credit (HELOC): A HELOC lets homeowners borrow against available equity and access funds as needed, with required repayment.
- Home equity loan: This option generally provides a lump sum based on available equity, typically with fixed monthly payments.
- Reverse mortgage: Homeowners age 62 or older may be able to convert some home equity into funds. However, reverse mortgages have residency requirements, and permanently moving from the home can affect the loan. Review the terms carefully before relying on this strategy.
These approaches can help cover assisted living costs without selling a home, but loan terms, interest, fees, and repayment requirements should be part of the decision.
Consider Rental Income as a Payment Strategy
For families who want to keep a home while in assisted living, renting the property may provide ongoing income to help offset monthly expenses.
A property management company can handle responsibilities such as finding tenants, collecting rent, and coordinating repairs. Although management services come with fees, they may make renting more practical for families who do not want to manage the property themselves.
Rental income can be part of a broader plan to afford care while keeping a house, especially when the family wants more time before deciding whether to sell.
Explore Veterans Benefits and Aid and Attendance
Some veterans and surviving spouses may qualify for VA Aid and Attendance benefits, which can help eligible individuals pay for long-term support, including services in some assisted living settings.
Eligibility depends on factors such as military service, financial circumstances, and the applicant’s need for assistance with Activities of Daily Living (ADL). Because eligibility and benefit amounts vary, families should review current VA requirements before including these benefits in their budget.
Starting early also gives you more time to gather the documentation needed for an application.
Review Long-Term Care Insurance Coverage
If your loved one has long-term care insurance, review the policy before comparing financing senior living options.
Depending on the policy, benefits may help cover some assisted living expenses.
Important details to review include:
- Daily or monthly benefit limits
- Elimination or waiting periods
- Covered services
- Maximum benefit periods
- Requirements for qualifying for benefits
Contacting the insurance provider early can clarify what the policy covers and what expenses the family may need to fund through other resources.
Look at Life Insurance Options
Some life insurance policies may offer ways to access funds during the policyholder’s lifetime.
A life settlement involves selling an eligible policy to a third party for a lump sum. The policyholder receives funds, but beneficiaries generally will not receive the original death benefit.
Some policies also offer accelerated death benefits, which may allow an eligible policyholder to access part of the death benefit while living.
Because these choices can affect beneficiaries, taxes, and long-term financial plans, review the details with the insurer and an appropriate financial professional.
Compare Costs With What Is Included
When weighing payment strategies, consider more than the monthly rate. Look at which everyday expenses and services are included.
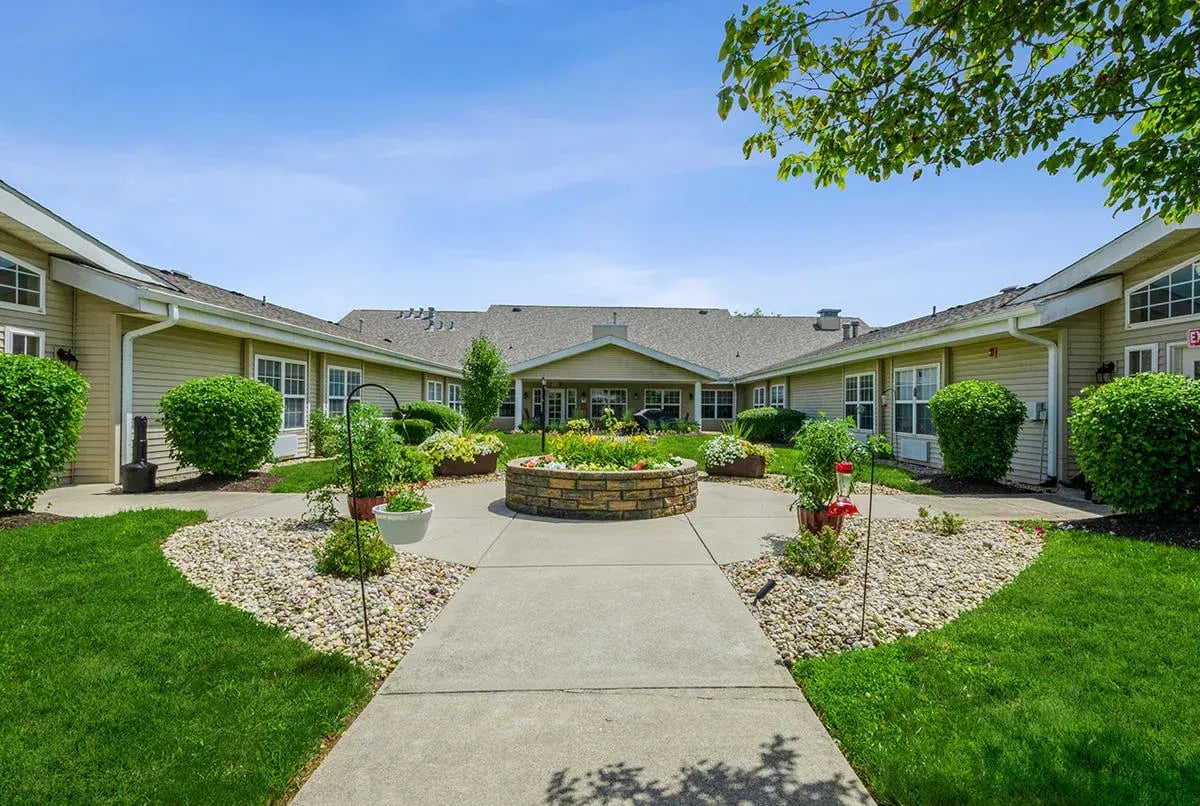
At Assisted Living at Worthington Place in Camby, residents have access to three daily meals, weekly housekeeping and laundry, transportation coordination, comfortable gathering spaces, and personalized assistance with daily routines. Its one-level layout and 39 private apartment homes also create the smaller, neighborly atmosphere associated with LakeHouse communities.
Families can also explore Worthington Place floor plans and pricing while estimating how senior living expenses compare with maintaining a house and paying separately for meals, utilities, transportation, upkeep, and support.
Get Professional Financial Guidance
A financial advisor or elder law attorney can help families understand how different strategies may affect taxes, estate plans, public benefits, and long-term goals. This can be especially useful when combining home equity, insurance, veterans' benefits, or other resources.
No single solution fits every family. Exploring senior living financing options before deciding can provide more flexibility and help you determine whether keeping the family home is financially practical.
For families considering Worthington Place in Camby, IN, understanding both available payment resources and what is included in community living can make the next step clearer.